The Doomsday Portfolio

I still remember when Hurricane Sandy hit the Jersey Shore back in 2012.

We lost power for roughly 10 days. Gas stations had lines stretching down the road. Supermarket shelves were picked clean. Ordinary conveniences disappeared.

I distinctly remember thinking, Why the hell don’t we have a generator?!

It was one of those moments when you came face-to-face with the fragility of systems you rely on.

Fast-forward 14 years, and a different set of vulnerabilities has me revisiting that feeling.

Just last week, AI-assisted researchers uncovered serious security flaws in PHP, software used to power much of the internet. The vulnerabilities were significant enough that government websites were temporarily taken offline while emergency patches were deployed.

Meanwhile, Microsoft reported that a state-linked hacking group had used autonomous AI tools to target hundreds of organizations, in some cases gaining privileged access to cloud systems in less than three hours.

It has me thinking: As our world becomes more technologically sophisticated and interconnected, there are also new points of vulnerability.

I’m by no means a cybersecurity expert and, besides some backup batteries, a case of drinking water, and some old MREs, I’m lacking in my doomsday preparedness.

But these recent events have forced the mental exercise of thinking more seriously about how prepared my own family would be if the systems we rely upon were suddenly unavailable.

The Secure Plan

In financial planning, I find it helpful to think about three different plans:

  • The Secure Plan: What do we need to protect ourselves and our families from meaningful disruptions?
  • The Comfortable Plan: What resources would allow us to enjoy the lifestyle we envision?
  • The Wealthy Plan: What would financial abundance and opportunity look like if things went exceptionally well?

Naturally, we spend a lot of time dreaming about the latter two.

But perhaps we should index some of our time, energy, and resources toward the first.

Just as we assess risk tolerance and risk capacity when constructing an investment portfolio, I think there’s a similar exercise worth undertaking with our personal preparedness.

How much disruption could your household comfortably absorb? How much inconvenience are you willing to tolerate? How much time and money are you willing to dedicate to protecting against events that may never occur?

I don’t think there’s one right answer. And I certainly haven’t figured out the right answer for my own family.

A Little Prepper 101

Here are some practical considerations I’ve been revisiting, ranging from simple precautions to more substantial investments in resilience.

Digital and financial security

  • A password manager (I use 1Password) with unique passwords, passkeys, and two-factor authentication.
  • Credit freezes with all three bureaus and an IRS Identity Protection PIN.
  • Automatic software updates + additional protection against SIM swapping.
  • A secure inventory of financial accounts, insurance policies, and important documents that a spouse or trusted person can access.

Basic household preparedness

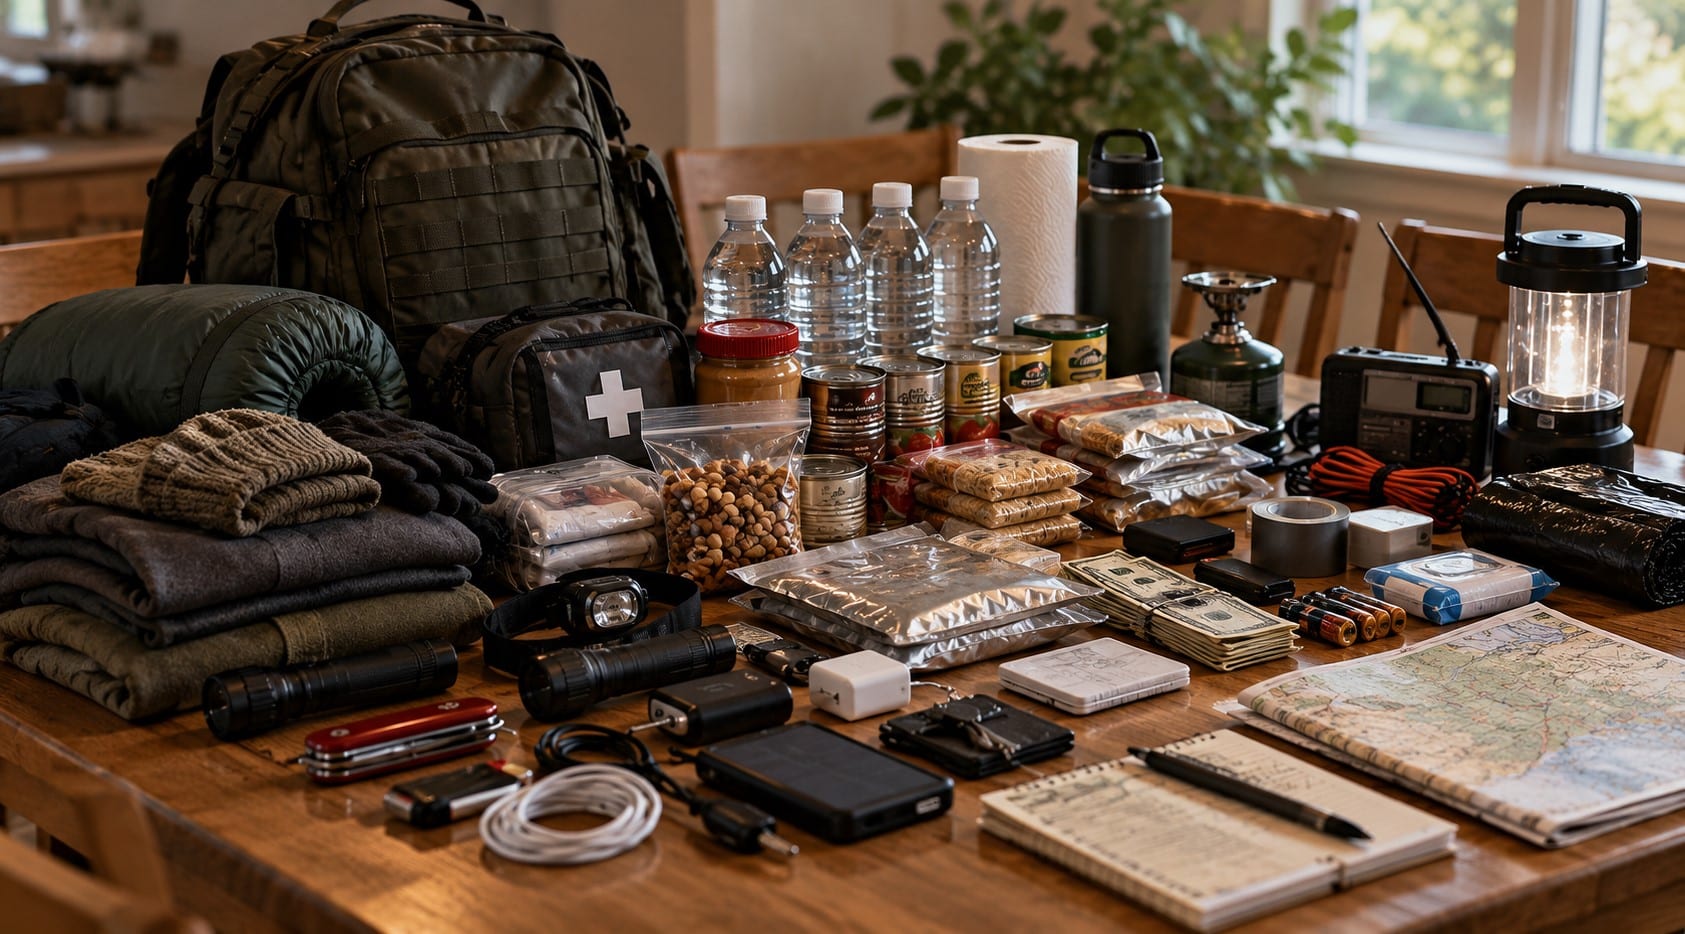
  • Several days of drinking water, shelf-stable food, and necessary medications.
  • Flashlights, batteries, first-aid supplies, and portable charging banks.
  • Some physical cash in case ATMs or electronic payment systems are unavailable.
  • A printed list of important contacts, account institutions, and emergency information.

Going a step further

  • A generator or backup battery system for essential appliances.
  • A reserve of fuel (stored safely and in accordance with local regulations).
  • A backup internet or communication option.
  • A family emergency plan, including where to meet and how to communicate if cellular networks are disrupted.

Admittedly, none of these ideas are revolutionary. Many are relatively inexpensive. Others require more meaningful investments.

And that’s where the risk-tolerance analogy becomes useful.

For some families, a few days of supplies and basic digital protections may be sufficient. Others might reasonably want to prepare for a week or two without electricity, banking access, or reliable communications.

The objective isn’t necessarily to prepare for the apocalypse. It’s to identify the disruptions that would most meaningfully affect your family and consider whether some modest preparation today could make tomorrow considerably less stressful.

Diversification Beyond Your Portfolio

We diversify investments to hedge against the unknown future.

We purchase insurance to protect downside risk.

We maintain emergency funds because life throws curveballs.

Perhaps our Secure Plan deserves the same thoughtful approach.

I haven’t arrived at any grand conclusions, just more conscious of how much of our everyday comfort depends on systems functioning exactly as expected.

And remembering Hurricane Sandy, I know firsthand that sometimes they don’t.

The point isn’t to spend our lives worrying about everything that could go wrong. It’s to build enough resilience that we can spend more of our lives enjoying everything that could go right.

Hope for the best. Prepare for the worst. And keep living fully in the meantime.
There Is No Perfect Time to Buy a House

Housing is really expensive.

I realize this isn’t breaking news. But the magnitude of what’s happened is worth appreciating.

Consider a hypothetical $500,000 home purchased in 2020.

With 20% down, a 2.88% mortgage, $10,000 in property taxes and $1,500 in homeowners insurance, the monthly carrying cost was roughly $2,620.

Home prices in the Middle Atlantic have since increased approximately 43%. That same house might cost around $715,000 today.

Put 20% down again and finance the rest at today’s roughly 7.3% mortgage rate and (even if we pretend taxes and insurance haven’t increased) the monthly carrying cost approaches $4,900.

Same house. 86% higher monthly cost.

The price of the house went up at the same time the price of borrowing money to buy it went up.

Brutal. And yet prices haven’t collapsed.

Part of the reason is supply.

Ezra Klein and Derek Thompson explore the topic of housing supply in their book, Abundance: many high-demand communities have spent decades making it increasingly difficult to build new housing.

I actually have this debate at my own dinner table.

My mom is the longest-serving councilperson in our small New Jersey town and is currently running for mayor. When it comes to new development, she worries about congestion, parking, and preserving the quaint character that attracted people to Keyport in the first place.

I get it.

But as a millennial, I’m witnessing my peers paying astronomical rents for remarkably little housing. I may or may not periodically accuse her of NIMBYism 😉.

She might use a different word.

Either way, the tension is pretty simple:

Many of us agree that we need more affordable housing. We just don’t necessarily want anyone to build more of it near us.

Meanwhile, millions of existing homeowners have another reason not to move:

they don’t want to give up their cheap mortgages.

Add it all together and the housing market is unusually stuck. Existing-home sales have been running near historically low levels despite a growing U.S. population.

Which inevitably leads to the question:

Is this a bad time to buy a house?

Personally, I think that’s the wrong question.

Because you aren’t buying the housing market.

You’re buying a house.

And whether you should buy one depends a lot more on which of the following people you are.

The First-Time Buyer

You don’t have a 3% mortgage to give up.

Unfortunately, you also don’t have years of accumulated home equity helping you buy the next house.

So you wait.

Maybe rates will come down.

Maybe.

Maybe home prices will fall.

Also possible.

Maybe both happen.

Sure.

But now we’re making market predictions.

And if mortgage rates fall substantially, you’re unlikely to be the only buyer who notices. Lower borrowing costs can bring more buyers into the market and support prices.

There is no rule requiring these variables to move conveniently for you.

Which is why I’d rather start with what we actually know.

Can you afford the house today?

Not assuming a future refinance or the home appreciating 5% per year.

At today’s price and today’s mortgage rate.

Can you make the down payment without gutting your emergency reserves or compromising the rest of your financial plan?

Can you comfortably afford the mortgage, taxes, insurance, maintenance and everything else that comes with owning a home?

And then our big one:

Do you reasonably expect to live there for at least the next five to seven years?

Buying and selling a house is expensive. The longer you own it, the more time you have to amortize those transaction costs and the less important it becomes whether your house is temporarily worth 5% less next year.

The Move-Up Buyer

This might be the most interesting housing problem today.

You bought your starter home years ago.

It’s appreciated substantially.

Awesome!

Except the larger home you planned to buy someday appreciated too.

And your existing house might be financed at 3%.

The next one might be financed above 7%.

You benefited enormously from rising home prices, only to find that the next rung of the housing ladder moved higher too.

That’s a predicament and it creates a powerful incentive to stay put.

“We’ll move when rates get back to 5%.”

Maybe that’s next year. Maybe it’s five years from now. Maybe rates fall to 5% and the house you want costs another $150,000.

Nobody knows.

Which is why the move-up decision needs to become about something bigger than mortgage rates.

What are you actually buying?

Another bedroom?

A better school district?

A yard?

A shorter commute?

Space for your parents?

A neighborhood where your kids can ride their bikes to their friends’ houses?

Maybe it’s simply the home where you picture spending the next fifteen years raising your family.

Those things have intangible value, which is part of what makes a primary residence an unusual asset.

It can build wealth over time, but I don’t necessarily agree with viewing it as an investment.

It’s primarily a personal-use asset, a place to live your life.

Not all of the value you receive from your home will show up on your balance sheet.

The Empty Nester

Then we get the opposite problem.

The kids are gone.

You’re walking around a 4,500-square-foot house wondering why you still have four bedrooms nobody sleeps in.

The financial-planning answer can seem obvious: downsize.

Except sometimes it isn’t.

Maybe your current house is paid off. Maybe it carries a tiny mortgage at an extraordinarily low rate. Maybe the smaller house or condo you actually want costs substantially more than you expected.

Add property taxes, HOA fees, moving expenses, transaction costs and potentially taxes on the sale, and suddenly “downsizing” isn’t synonymous with “saving money.”

More importantly:

What are you actually optimizing for?

Less maintenance?

Walkability?

Living closer to your children and grandchildren?

More freedom to travel?

A first-floor primary bedroom?

A community that makes aging in place easier?

Or maybe you simply love the house you’ve lived in for 30 years and have absolutely no interest in leaving it. That’s okay too.

Personal finance should help you make the life decision not make the life decision for you.

Hindsight 20/20

There’s a behavioral-finance problem underneath all of this.

Of course you should have bought a house in 2019.

Of course you should have refinanced at 2.75%.

Those decisions seem obvious because we know what happened next.

We don’t have that luxury today.

Five years from now, maybe we’ll wonder why anyone bought a house in 2026.

Or maybe we’ll wonder why anyone waited.

Trying to perfectly time a home purchase is particularly difficult because you’re effectively forecasting two markets at once:

  1. The price of the house.
  2. The price of the money you’re borrowing to buy it.

I’d rather build a financial plan that doesn’t require getting either prediction right.

So when clients ask whether now is the right time to buy, I’d focus on five questions:

  1. Can I afford the down payment without compromising the rest of my financial plan?
  2. Can I comfortably afford this house at today’s price and today’s interest rate?
  3. Does the plan still work if I can’t refinance and the house doesn’t appreciate for several years?
  4. Am I reasonably confident I’ll live here for at least the next 5-7 years?
  5. *MOST IMPORTANT* Does this home make sense for the life you’re building?

If the answers are yes, you don’t need a housing-market forecast.

If the answers are no, a prediction that mortgage rates are about to fall probably shouldn’t change your mind.

The goal isn’t to buy a house at the perfect time.

It’s to buy the right house, at a price you can afford, at a time when it makes sense for your life. With enough time, the short-term housing market matters a whole lot less.